After a workplace accident, an insurer may accept responsibility yet offer less than the injuries…
How Do Section B Accident Benefits Work in Nova Scotia?
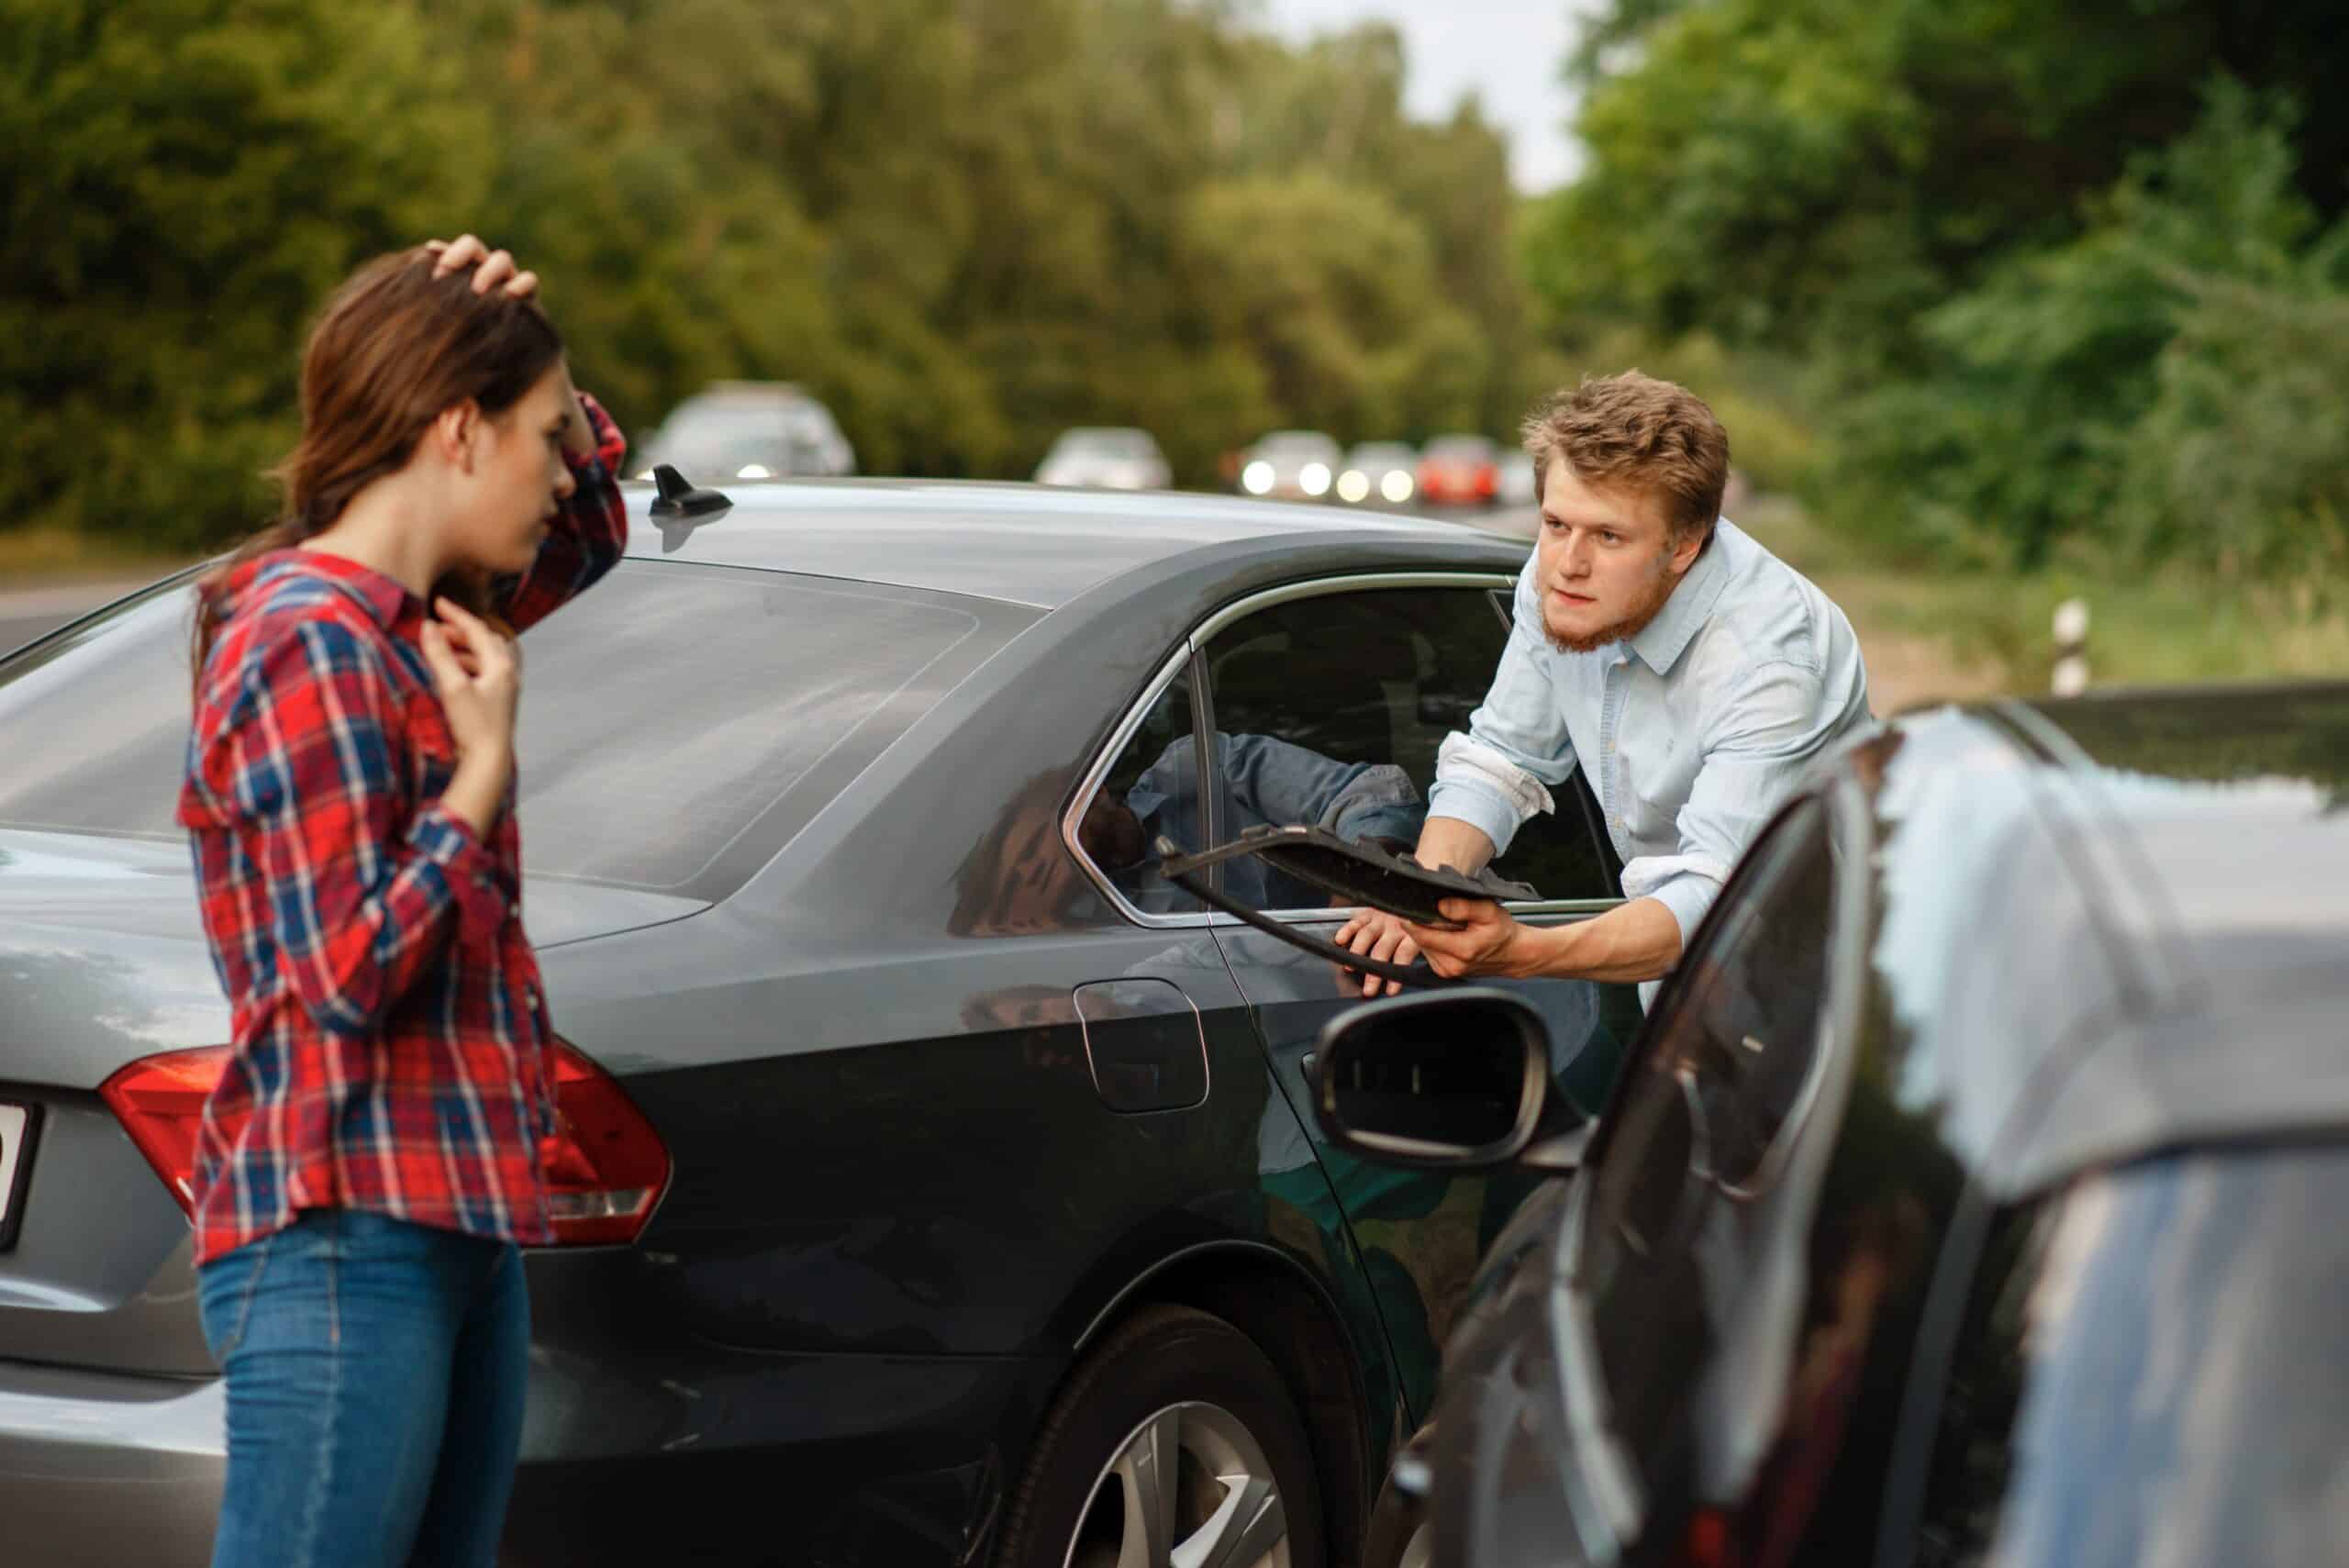
If you’ve been in a car accident in Nova Scotia, the insurance paperwork that follows can feel overwhelming, especially when you’re still hurting. Section B accident benefits exist precisely for that situation. They’re a no-fault benefit built into every standard automobile insurance policy in the province, which means you can access them regardless of who caused the crash. Knowing how Section B works gives you a clearer picture of what support you’re entitled to and how to actually pursue it.
What Section B Covers and Who Qualifies
Section B is a mandatory part of every standard automobile insurance contract in Nova Scotia under the province’s Insurance Act. Drivers, passengers, and pedestrians injured in a motor vehicle accident can all consult an injury law firm in Halifax to figure out whether their situation qualifies – the eligibility rules aren’t always straightforward. Coverage applies whether you were at the wheel, riding as a passenger, or struck as a pedestrian. Your own insurer pays these benefits. You don’t need to prove the other driver was responsible before you can access them – that’s the whole point of no-fault. A tort claim is different; fault and liability must be established first. Section B sits alongside your liability and collision coverage as a standard component, not an optional add-on.
Medical and Rehabilitation Benefits
The medical and rehabilitation benefit pays for reasonable and necessary treatment costs arising directly from the accident. Physician visits, physiotherapy, chiropractic care, massage therapy, prescription medication, assistive devices like crutches or braces, all of these can qualify. In Nova Scotia, the standard limit sits at $25,000 per person per accident, and you generally have four years from the collision date to incur eligible costs within that window. Treatment must be considered medically necessary; your insurer may request documentation from your healthcare providers to confirm it. So keep thorough records of every appointment, prescription, and invoice from day one. If your treatment costs approach or exceed that limit, a legal advisor can help you assess whether a tort claim against the at-fault driver might cover the gap between what Section B pays and what your actual recovery requires.
Income Replacement and Death Benefits
Section B also pays income replacement if your injuries keep you off work. The benefit equals 80% of your net weekly income up to the policy maximum, it helps, but it won’t fully replicate a high earner’s salary. Payments begin after a waiting period, and you’ll need medical documentation confirming you can’t perform your regular job duties. Death benefits are available too, when someone dies from the accident. A surviving spouse receives a lump-sum payment; dependent children receive a separate amount per child. There’s also a funeral expense benefit built into the policy. Because these amounts are defined in the standard policy and your insurer must pay them regardless of fault, they’re typically faster to access than compensation pursued through a civil claim.
How to File a Section B Claim in Nova Scotia
Start by notifying your own automobile insurer promptly after the accident. Most policies require you to report the collision as soon as reasonably possible, and delays can create real headaches with your claim. Your insurer will ask you to complete an Accident Benefits Application form covering your personal details, the circumstances of the accident, your injuries, and your employment information if you’re seeking income replacement. Before you submit, gather as much documentation as you can, police report numbers, medical records, pay stubs, and the names of all treating healthcare providers. Once your insurer receives the completed application, they’re obligated to respond within a set timeframe and begin processing eligible expenses. Keep copies of everything you send and note the dates; a paper trail protects you if a dispute comes up later.
Deadlines and Documentation You Need to Know
Here’s the thing – strict deadlines are attached to Section B claims, and missing them can jeopardize your access to benefits. The general rule under the Insurance Act requires written notice to your insurer within 30 days of the accident, though that window can sometimes stretch to 90 days if you have a reasonable explanation for the delay. Proof of loss – meaning the formal documentation supporting your specific claim, must typically follow within 90 days of each incurred expense. Medical reports should be signed by a licensed physician and describe both the diagnosis and the expected recovery timeline. If you’re claiming income replacement, you’ll need a letter from your employer confirming your pre-accident earnings and your inability to work. And keep in mind that vague or general medical notes won’t carry much weight; the documentation needs to tie your condition specifically back to the collision date.
When a Claim Gets Disputed or Denied
Insurers don’t always approve Section B claims without pushback. A claim can be denied on the grounds that treatment wasn’t medically necessary, that expenses fell outside the covered period, or that your injuries weren’t severe enough to prevent work. You may also receive approval for less than you claimed. But you have the right to dispute those decisions. Nova Scotia’s insurance legislation provides a formal process for resolving disagreements between policyholders and insurers, one that can involve an independent medical examination or formal arbitration. If your insurer relies on a medical opinion contradicting your own doctor’s findings, you’re entitled to challenge it. This is where legal advice tends to make an outsized difference; someone who understands how insurers build their cases can identify where the dispute has the most merit and what evidence you’d need to succeed.
Conclusion
Section B accident benefits in Nova Scotia give injured people a direct path to medical coverage and income support after a collision, without waiting for fault to be sorted out. The catch is that the details matter enormously – what’s covered, the filing deadlines, your insurer’s conduct, and the severity of your injuries all shape the outcome. Medical and rehabilitation expenses up to the policy limit, income replacement tied to your net earnings, death and funeral benefits for surviving family members – these are the pillars of what the benefit provides. And if your claim runs into problems, or your costs exceed what Section B pays, looking into your broader legal options is a reasonable next step.